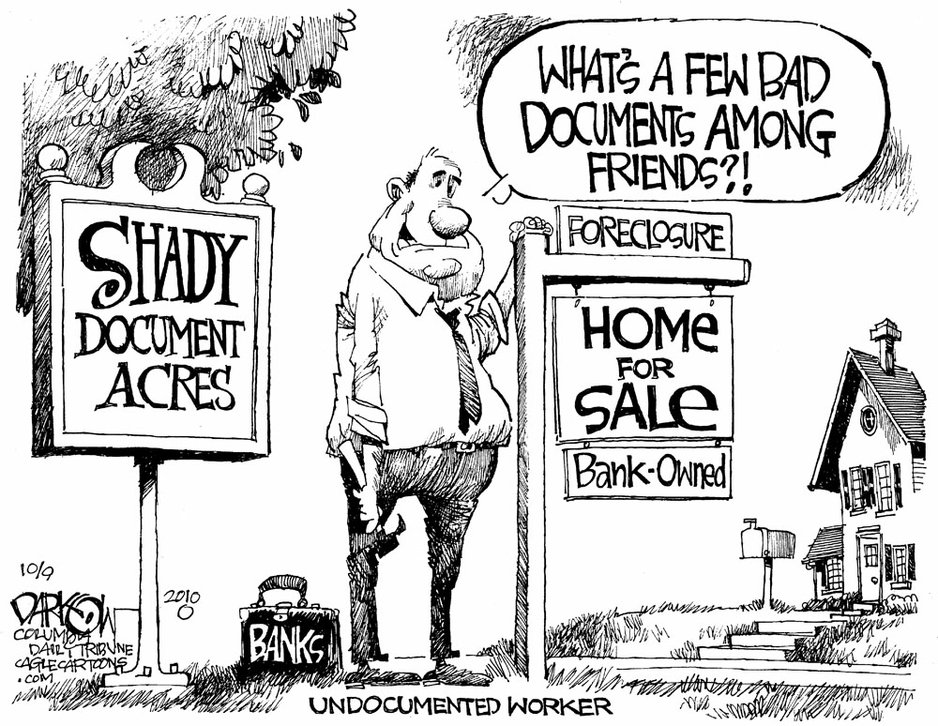
THIS REPORT DESCRIBES THE DIFFERENT WAYS THAT MORTGAGE LENDERS CAN TRICK HOMEOWNERS INTO GIVING UP THEIR HOMES, AND A LEGAL REMEDY TO RECOVER TILA VIOLATION FINES AND possibly VOID THE LENDERS SECURITY INTEREST IN THE PROPERTY.
I. ORIGINATION OF THE LOAN
Solicitations. Predatory mortgage lenders target low and moderate income and minority neighborhoods for extensive marketing. They advertise through direct mail, telephone and door to door solicitations, flyers stuffed in mailboxes, and highly visible signs in these neighborhoods. They advertise on radio stations with a large minority audience and employ television commercials that feature celebrity athletes. Many companies deceptively tailor their solicitations to resemble Social Security or other government checks to prompt homeowners to open the envelopes and otherwise deceive them about the transaction.
Home Improvement Scams. Predatory mortgage lenders use local home improvement companies essentially as mortgage brokers to solicit loan business. These companies target homeowners and solicit them to execute home improvement contracts. The company may originate a mortgage loan to finance the home improvements and sell the mortgage to a predatory mortgage lender, or steer the homeowner directly to the predatory lender for financing of the home improvements. There are many scams involving home improvements.
With FHA Title 1 home improvement loans; sometimes the contractor falsely claims that HUD will guarantee that the work will be done properly and/or that HUD will pay for the home improvements. In reality, HUD only guarantees to the holder of the mortgage that HUD will pay the mortgage if the homeowner defaults. HUD then pursues the homeowner for payment.
The homeowners are often grossly overcharged for the work, which the contractors often perform shoddily and fail to complete as agreed. They sometimes damage the homeowner’s personal property in the process. In other cases, the contractor fails to obtain required city or county permits, thereby making sure that local code officials do not inspect the work for compliance with local codes and do not require that the shoddy work be corrected.
Some predatory mortgage lenders issue payments to the home improvement contractor without ensuring that the work has been properly completed according to the terms of the contract. Some predatory mortgage lenders issue checks payable solely to the contractor, thereby bypassing the homeowner.
Some home improvement companies solicit home improvement contracts with the intent to have the work financed and immediately begin the work prior to the expiration of the homeowner’s three-day right to cancel the transaction.
Some home improvement contractors have the homeowner sign a cash home improvement contract for an amount the homeowner cannot afford in a lump sum. When the contractor arranges financing with the predatory mortgage lender and the homeowner objects to the terms of the predatory loan, the contractor threatens to place a lien on the property and sue the homeowner unless the homeowner goes through with the financing.
Predatory mortgage lenders deny responsibility for the overpriced, shoddy and incomplete work, even though they previously arranged for these home improvement companies to solicit loan business for them, and sometimes referred the homeowner directly to the unscrupulous contractor.
Mortgage Broker’s Fees and Kickbacks.
Predatory mortgage lenders also originate loans through local mortgage lenders who act as “bird dogs”, or finders for the lenders. These brokers represent to the homeowners that they are working for them to help them obtain the best available loan, and the homeowners usually pay a broker’s fee. In fact, the brokers are working for predatory lenders, who pay brokers kickbacks to refer borrowers to them. Mortgage brokers steer borrowers to the lender who will pay him or her the highest fee, not to the lender who will give the borrower the lowest interest rate and fees. Without the borrower’s knowledge, the lender charges an interest rate higher than that for which the borrower would otherwise qualify in order to pass on to the borrower the cost of the kickback. On loan closing documents, the industry uses euphemisms or their abbreviations for these kickbacks: yield spread premiums (YSP) and service release fees (SRF). The industry also calls this bonus upselling or par-plus premium pricing; we call it paying unlawful kickbacks.
Steering to High Rate Lenders. Banks and mortgage companies steer customers with less than perfect credit to high rate lenders, often a subsidiary or affiliate of the bank or mortgage company. Some banks and mortgage companies steer customers – especially minorities – who may have good credit and would be eligible for a conventional loan to high cost lenders. Sometimes the customer is steered away even before completing a loan application. Kickbacks or referral fees are paid as an incentive to steer the customer to a higher rate loan. This practice of steering these applicants to high rate lenders is called downstreaming. On the other hand, when people with good credit go to predatory mortgage lenders, the lender does not upstream the applicant to a bank or conventional mortgage company for a low cost mortgage loan.
Making Unaffordable Loans. Some predatory mortgage lenders purposely structure loans with monthly payments that they know the borrower cannot afford so that when the homeowner is led inevitably to the point of default, she will return to the lender to refinance the loan, and the lender can impose additional points and fees. Other predatory mortgage lenders, called hard lenders, intentionally structure the loans with payments the homeowner cannot afford in order to lead to foreclosure so that they may acquire the house and the valuable equity in the house at a foreclosure sale.
Falsified or Fraudulent Applications. Some predatory mortgage lenders knowingly make loans to unsophisticated homeowners who do not have sufficient income to repay the loan. Often such lenders plan to sell the loan on the secondary market, especially through a process of securitization. This process generally involves oversight and due diligence by the purchaser to ensure that each borrower appears to have sufficient income to repay the loan. Knowing that these loan files may be reviewed at a later date by subsequent purchasers, such lenders have the borrowers sign a blank application form and then insert false information on the form, claiming that the borrower has employment income that she does not, so it appears that she can make the payments.
Adding Inappropriate Cosigners. This is done to create the false impression that the borrower can afford the monthly payments, even though the lender is well aware that the cosigner has no intention of contributing to the payments. Often, the lender requires the homeowner to transfer half ownership of the house to the cosigner. The homeowner thereby loses half the ownership of the home and is saddled with a loan she cannot afford to repay.
Incapacitated Homeowners. Some predatory lenders make loans to homeowners who are clearly mentally incapacitated. They take advantage of the fact that the homeowner does not understand the nature of the transaction or the papers that she signs. Because of her incapacity, the homeowner does not understand that she has a mortgage loan, does not make the payments, and is subject to foreclosure and subsequent eviction.
Forgeries. Some predatory lenders forge loan documents. In an ABC Prime Time Live news segment that aired April 23, 1997, a former employee of a high cost mortgage lender reported that each of the lender’s branch offices had a “designated forger” whose job it was to forge documents. Forgeries are used to refinance a customer into another high cost mortgage with the same lender, to show apparent approval for payouts to home improvement contractors when the work is shoddy and/or incomplete, and to show apparent approval for such charges as credit insurance premiums.
High Annual Interest Rates. Because the purpose of engaging in predatory lending is to reap the benefit of high profits, these lenders always charge extremely high interest rates. This drastically increases the cost of borrowing for homeowners, even though the lenders’ risk is minimal or nonexistent. Predatory lenders may charge rates of 10% and more, substantially higher than the rates of 7% to 8% on conventional mortgages.
High Points. Legitimate lenders charge discount points to borrowers who wish to buy down the interest rate on the loan. Predatory lenders charge high points, but offer no corresponding reduction in the interest rate. These points are imposed through prepaid finance charges (or points or origination fees), which are usually 3% to 10%, but may be as much as 20%, of the loan. The borrower does not pay these points with cash at closing. Rather, the points are always financed as part of the loan. This increases the amount borrowed, which generates more actual interest to the lender.
Balloon Payments. Predatory lenders frequently structure loans so that the borrower’s payments are applied primarily to interest, and at the end of the loan period the borrower still owes most or all of the principal amount borrowed. The last payment balloons to an amount often equal to 85% or so of the original principal amount of the loan. The homeowner cannot afford to pay the balloon payment, and either loses the home through foreclosure or is forced to refinance with the same or another lender for an additional term and additional points, fees, and closing costs.
Negative Amortization. This involves structuring the loan so that interest is not amortized over the term. Instead, the monthly payment is insufficient to pay off accrued interest and the outstanding loan balance therefore increases each month. At the end of the loan term, the borrower may owe more than the amount originally borrowed. With negative amortization, there will almost always be a balloon payment at the end of the loan.
Credit Insurance – Insurance Packing. Predatory mortgage lenders market and sell credit insurance as part of their loans, often without the knowledge or consent of the borrower. Typical insurance products sold in connection with loans include credit life, credit disability, credit property, and involuntary unemployment insurance, and debt cancellation and suspension agreements. Lenders frequently charge exorbitant premiums, which are not justified based on the extremely low actual loss payouts. Frequently, credit insurance is sold by an insurance company which is either a subsidiary of the lender or which pays the lender substantial commissions. They over-insure borrowers by providing insurance for the total indebtedness, including principal and interest, rather than merely the principal amount of the loan. They also under-insure borrowers by providing insurance for less than the outstanding principal balance and less than the full term of the loan. In short, credit insurance becomes a profit center for the lender and provides little or no benefit to the borrower.
Padding Closing Costs. In this scheme, certain costs are increased above their market value as a way of charging higher interest rates. Examples include charging document preparation fees of $350 or credit report fees of $300, which are many times the actual cost
Inflated Appraisal Costs. In most mortgage loan transactions, the lender requires an appraisal. Most appraisals include a detailed report of the condition of the house, both interior and exterior, and prices of comparable homes in the area. Others are “drive-by” appraisals, done by someone simply looking at the outside of the house. The former naturally costs more than the latter. However, in some cases, borrowers are charged for a detailed appraisal, when only a drive-by appraisal was done.
Inflated Appraisals. In order to make large loans, predatory mortgage lenders arrange for appraisals that inflate the true value of the house. The homeowner is then stuck with the new mortgage, unable to sell the house or refinance in the future because the mortgage balance exceeds the true value of the home.
Padded Recording Fees. Mortgage transactions usually require that documents be recorded at the local courthouse, and state or local laws set the fees for recording the documents. Predatory mortgage lenders often charge the borrowers a recording fee in excess of the actual amount established by law.
Increased interest rate after default. Some predatory mortgage lenders make loans that allow the interest rate to increase if the borrower defaults on the loan, which makes it even more difficult for the homeowner to catch up the payments when they recover from a temporary financial loss.
Advance Payments from Loan Proceeds. Some predatory mortgage lenders make loans in which more than two monthly payments are consolidated and paid in advance from the loan proceeds. The payments can be used to mask a loan that is being made to a borrower who has no reasonable prospect of paying the loan. By creating this initial reserve of advance payments, the lender can use this reserve to keep the loan current for a period and make the loan appear justified. In addition, the lender’s deducting these payments from the loan proceeds gives the lender free use of the borrower’s money that the borrower is paying interest on.
Bogus Mortgage Broker Fees. In some cases, predatory lenders finance mortgage broker fees when the borrower never met or knew of the broker. This is another way such lenders increase the cost of the loan for their own benefit.
Unbundling. This is another way of padding costs by breaking out and itemizing charges that are duplicative or should be included under other charges. An example is charging a loan origination fee (which should cover all costs of initiating the loan) and then imposing separate, additional charges for underwriting and loan preparation.
Prepayment Penalties and Fees. Predatory lenders often impose exorbitant prepayment penalties. This is done in an effort to lock the borrower into the predatory loan for as long as possible by making it difficult for her to refinance the mortgage or sell the home. For example, a homeowner has a high cost mortgage loan with a balance of $132,000 which she is unable to refinance at a lower rate because there is a $6,200 prepayment penalty due at the end of her fifth year paying this mortgage. Predatory mortgage lenders often charge a fee for informing the borrower or a lender of the balance due to pay off the existing mortgage loan. The loan documents almost never authorize such a fee. These practices provide back end interest for the lender if the borrower does prepay the loan.
Mandatory Arbitration Clauses. Pre-dispute, mandatory, binding arbitration clauses limit the rights of borrowers to seek relief through the judicial process for any and all claims and defenses the borrower may have against the mortgage lender, mortgage broker, or other party involved in the loan transaction. By inserting these clauses in the loan documents, some lenders attempt to obtain an unfair advantage by relegating their borrowers to a forum perceived to be more favorable to the lender. This perception exists because discovery is not a matter of right, but is within the discretion of the arbitrator; the proceedings are private; arbitrators need not give reasons for their decisions or follow the law; a decision in any one case will have no precedential value; judicial review is extremely limited; and injunctive relief and punitive damages are not available. Furthermore, the lender is not required to arbitrate claims it may have against the borrower. If the borrower defaults on the loan, the lender proceeds directly to foreclosure.
Flipping. Loan flipping happens when mortgage lenders and mortgage brokers aggressively try to persuade homeowners to refinance repeatedly when the new loan does not have a reasonable, tangible net benefit to the borrower considering all the circumstances, including the terms of both the new and refinanced loan, the cost of the new loan, and the borrower’s circumstances. Reduction of monthly payments alone is not a tangible benefit to the borrower. Predatory mortgage lenders and brokers hook the borrower into refinancing by offering lower monthly payments and lower interest, refinancing out from under a balloon payment or variable rate mortgage, or by offering additional cash. Each time the borrower refinances the amount of the loan increases to include additional origination fees, points, and closing costs. Also, the term of the loan is extended. If the loan amount is increased and the term is extended, the borrower will pay much more interest than if the borrower had kept the original loan. If the borrower actually needs more money, it would be better if the lender made a second, separate loan for the additional amount needed. A powerful example of the exorbitant costs of flipping is the case of Bennett Roberts, who had eleven loans from a high cost mortgage lender within a period of four years. See Wall Street Journal, April 23, 1997. Mr. Roberts was charged in excess of $29,000 in fees and charges, including 10 points on every financing, plus interest, to borrow less than $26,000. The purpose of flipping is to keep the borrower in a constant state of indebtedness. To paraphrase from the famous Eagles’ song, “Welcome to the Hotel California, you can check in but you can never check out.”
Recommending Default in connection with a Refinance. Predatory mortgage lenders and brokers often recommend or encourage the borrower to stop making payments on their existing mortgage loan and other loans or debts because they will refinance “soon.” However, the closing on the refinance is delayed and sometimes never happens. If the refinancing occurs, the borrower feels compelled to go through with the closing despite the high interest rate, points, and fees and other abusive features of the loan because the other creditors are demanding payment on their loans, possibly threatening foreclosure or other legal action. Also, the new lender charges an interest rate higher than originally promised, and justifies the higher rate by telling the borrower that their credit records now show no or slow payments on their bills.
Modification or Deferral Fees. Some predatory mortgage lenders charge borrowers a fee or other charge to modify, renew, extend or amend a mortgage loan or to defer any payment due under the terms of the mortgage loan, even though the contract does not authorize such a fee.
Spurious Open End Mortgages. In order to avoid making required disclosures to borrowers under the Truth in Lending Act, many lenders are making “open-end” mortgage loans. Although the loans are called “open-end” loans, in fact they are not. Instead of creating a line of credit from which the borrower may withdraw cash when needed, the lender advances the full amount of the loan to the borrower at the outset. The loans are non-amortizing, meaning that the payments are interest only, so that the balance is never reduced.
Paying Off Low Interest Mortgages. A predatory lender usually insists that its mortgage loan pay off the borrower’s existing low cost, purchase money mortgage. Instead of lending the borrower only the amount he actually needs in a second, separate loan, the lender makes a new loan paying off the current mortgage. The homeowner loses the benefit of the lower interest rate and ends up with a higher interest rate and a principal amount that is much higher than necessary.
Paying Off Forgivable Loans and No-interest Loans. Many low income homebuyers obtain down payment assistance grants from state and local agencies. These grants are made in the form of second mortgages that are forgiven as long as the homebuyer remains in the home for five or ten years. Other government programs allow low income and elderly homeowners to obtain grants for necessary home improvement work to bring homes up to code standards. These grants are also made in the form of mortgage loans that are forgiven as long as the homeowner remains in possession of the home for five or ten years. When many predatory mortgage lenders make loans to these homeowners, they insist that these forgivable loans be paid off (to increase the amount borrowed) even though these loans would be forgiven in a matter of a few short years. Habitat for Humanity provides home purchase mortgage loans on which no interest is charged to low income homebuyers. Predatory mortgage lenders have targeted Habitat for Humanity homebuyers in Georgia and North Carolina for high cost mortgage loans, offering “cash out” loans to entice them and then requiring them to paying off their no interest Habitat mortgage loans.
Shifting Unsecured Debt Into Mortgage. Mortgage lenders badger homeowners with advertisements and solicitations that tout the “benefits” of consolidating bills into a mortgage loan. The lender fails to inform the borrower that consolidating unsecured debt such as credit cards and medical bills into a mortgage loan secured by the home is a bad idea. If a person defaults on an unsecured debt, they do not lose their home. If a homeowner rolls their unsecured debt into their mortgage loan and default on their mortgage payments, they can lose their home. Furthermore, since unsecured debt generally is paid off between three and five years, shifting unsecured debt into a mortgage loan extends the payoff period to 15 to 30 years. Paying off unsecured debt with a mortgage loan also necessarily increases closing costs because they are often calculated on a percentage basis, thereby increasing the loan balance. Whereas the old total monthly household debt payments may in some cases be less than the monthly payments on the new mortgage loan, the monthly mortgage payments are often more than the previous mortgage payments, thus exacerbating the risk that the homeowner will lose the home to foreclosure.
Making Loans in Excess of 100% Loan to Value (LTV). Some lenders are making loans to homeowners in amounts that exceed the fair market value of the home. This makes it very difficult for the homeowner to refinance the mortgage or to sell the house to pay off the loan, thereby locking the homeowner into a high cost loan. Normally, if a homeowner goes into default and the lender forecloses on a loan, the foreclosure sale generates enough money to pay off the mortgage loan and the borrower is not subject to a deficiency claim. However, where the loan is 125% LTV, a foreclosure sale may not generate enough to pay off the loan, and the lender may pursue the borrower for the deficiency.
II. SERVICING OF THE LOAN
Force Placed Insurance. Lenders require homeowners to carry homeowner’s insurance, with the lender named as a loss payee. Mortgage loan documents allow the lender to force place insurance when the homeowner fails to maintain the insurance, and to add the premium to the loan balance. Some predatory lenders force place insurance even when the homeowner has insurance and has provided proof of insurance to the lender. The premiums for the force placed insurance are frequently exorbitant. Often the insurance carrier is a company affiliated with the lender, and the force placed insurance is padded because it covers the lender for risks or losses in excess of what the lender may require under the terms of the loan.
Daily Interest When Payments Are Made After Due Date. Most mortgage loans have grace periods, during which a borrower may make the monthly payment after the due date without incurring a late charge. The late charge often is assessed as a percentage of the late payment. However, many lenders also charge daily interest based on the outstanding principal balance. While it may be proper for a lender to charge daily interest when the loan so provides, it is deceptive for a lender to charge a late fee as well as daily interest when a borrower pays before the grace period expires.
Late fees. Some predatory mortgage lenders charge excessive late fees, such as 10% of the payment due. Sometimes they charge this fee more than once for only one late payment.
III. COLLECTION OF THE LOAN
Abusive Collection Practices. In order to maximize profits, predatory lenders either set the monthly payments at a level the borrower can barely sustain or structure the loan to trigger a default and a subsequent refinancing. Adding insult to injury, the lenders use aggressive collection tactics to ensure that the stream of income flows uninterrupted. The collection departments call homeowners at all hours of the day and night, including Saturday and Sunday, send late payment notices (in some cases, even when the lender has received timely payment or even before the grace period expires), send telegrams, and even send agents to hound homeowners, who are often elderly widows, into making payments. These abusive collection tactics often involve threats to evict the homeowners immediately, even though lenders know they must first foreclose and follow eviction procedures. The resulting impact on homeowners, especially elderly homeowners, can be devastating.
High Prepayment Penalties. See description above. When a borrower is in default and must pay the full balance due, predatory lenders will often include the prepayment penalty in the calculation of the balance due.
Flipping. See description above. When a borrower is in default, predatory mortgage lenders often use this as an opportunity to flip the homeowner into a new loan, thereby incurring additional high costs and fees.
Call provision. Some predatory mortgage lenders make loans with call provisions, which permit the holder of the mortgage, in its sole discretion, to accelerate the indebtedness, regardless of whether the borrower’s payments are current and the homeowner is otherwise in compliance with the terms of the loan.
Foreclosure Abuses. These include persuading borrowers to sign deeds in lieu of foreclosure, giving up all rights to protections afforded under the foreclosure statute, sales of the home at below market value, sales without the opportunity to cure the default, and inadequate notice which is either not sent or backdated. We have even seen cases of “whispered foreclosures”, in which persons conducting foreclosure sales on courthouse steps have ducked around the corner to avoid bidders so that the lender was assured he would not be out-bid. Finally, foreclosure deeds have been filed in courthouse deed records without a public foreclosure sale.
The above is a reprinted with permission from LegalAid-GA.org
END
DISCOVER THE POWER OF TILA
You can use The Truth In Lending Act (“TILA”) as a legal remedy to recover TILA violation fines and possibly void the lenders security interest in the property. The Act is in Title I of the Consumer Credit Protection Act and is implemented by the Federal Reserve Board via The Act is in Title I of the Consumer Regulation Z (12 C.F.R. Part 226).The Regulation has effect and force of federal law. “TILA is to be liberally construed in favor of consumers, with creditors who fail to comply with TILA in any respect becoming liable to consumer regardless of nature of violation or creditors’ intent.”
If your loan was after September 30, 1995 (that’s when the teeth were put into TILA) and never consummated you can rescind your loan Pursuant to the Federal Truth in Lending Act (“TILA”), You have the right to rescind the transaction within 3 days of receipt (The rescission period clock never starts ticking until the transaction is consummated) of his/her notice of his/her right of rescission and all other material disclosures required by TILA and the regulations therein. (15 U.S.C. §1635(a).
What is the right of rescission?
Truth-in-Lending Act (TILA) Consumer Credit Protection Act passed in 1969.
Truth in lending act — Regulation Z
The Truth in Lending Act (TILA), Title I of the Consumer Credit Protection Act, is aimed at promoting the informed use of consumer credit by requiring disclosures about its terms and costs. In general, this applies to each individual or business that offers or extends credit when the credit is offered or extended to consumers; the credit is subject to a finance charge or is payable by a written agreement in more than four installments; the credit is primarily for personal, family or household purposes; and the loan balance equals or exceeds $25,000.00 or is secured by an interest in real property or a dwelling. TILA is intended to enable the customer to compare the cost of cash versus credit transaction and the difference in the cost of credit among different lenders. The regulation also requires a maximum interest rate to be stated in variable rate contracts secured by the borrower’s dwelling, imposes limitations on home equity plans that are subject to the requirements of certain sections of the Act and requires a maximum interest that may apply during the term of a mortgage loan. TILA also establishes disclosure standards for advertisements that refer to certain credit terms. In addition to financial disclosure, TILA provides consumers with substantive rights in connection with certain types of credit transactions to which it relates, including a right of rescission in certain real estate lending transactions, regulation of certain credit card practices and a means for fair and timely resolution of credit billing disputes. This discussion will be limited to those provisions of TILA that relate specifically to the mortgage lending process, including:
1) Early and final Regulation Z disclosure requirements
2) Disclosure requirements for ARM loans
3) Right of rescission
4) Advertising disclosure requirements
TILA requires lenders to make certain disclosures on loans subject to the Real Estate Settlement Procedures Act (RESPA) within three business days after their receipt of a written application. This early disclosure statement is partially based on the initial information provided by the consumer. A final disclosure statement is provided at the time of loan closing. The disclosure is required to be in a specific format and include the following information:
- Name and address of creditor
- Amount financed
- Itemization of amount financed (optional, if Good Faith Estimate is provided)
- Finance charge
- Annual percentage rate (APR)
- Variable rate information
- Payment schedule
- Total of payments
- Demand feature
- Total sales price
- Prepayment policy
- Late payment policy
- Security interest
- Insurance requirements
- Certain security interest charges
- Contract reference
- Assumption policy
- Required deposit information
Disclosure Requirements for ARM Loans:
If the annual percentage rate on a loan secured by the consumer’s principal dwelling may increase after consummation and the term of the loan exceeds one year, TILA requires additional adjustable rate mortgage disclosures to be provided, including:
o The booklet titled Consumer Handbook on Adjustable Rate Mortgages, published by the Board and the Federal Home Loan Bank Board or a suitable substitute.
o A loan program disclosure for each variable-rate program in which the consumer expresses an interest. The loan program disclosure shall contain the necessary information as prescribed by Regulation Z.
TILA requires servicers to provide subsequent disclosure to consumers on variable rate transactions in each month an interest rate adjustment takes place.
Right of Rescission:
In a credit transaction in which a security interest is or will be retained or acquired in a consumer’s principal dwelling, each consumer whose ownership is or will be subject to the security interest has the right to rescind the transaction. Lenders are required to deliver two copies of the notice of the right to rescind and one copy of the disclosure statement to each consumer entitled to rescind. The notice must be on a separate document that identifies the rescission period on the transaction and must clearly and conspicuously disclose the retention or acquisition of a security interest in the consumer’s principal dwelling; the consumer’s right to rescind the transaction; and how the consumer may exercise the right to rescind with a form for that purpose, designating the address of the lender’s place of business.
In order to exercise the right to rescind, the consumer must notify the creditor of the rescission by mail, telegram or other means of communication. Notice is considered given when mailed, filed for telegraphic transmission or sent by other means, when delivered to the lender’s designated place of business. The consumer may exercise the right to rescind until midnight of the third business day following consummation of the transaction; delivery of the notice of right to rescind; or delivery of all material disclosures, whichever occurs last. When more than one consumer in a transaction has the right to rescind, the exercise of the right by one consumer shall be effective for all consumers.
When a consumer rescinds a transaction, the security interest giving rise to the right of rescission becomes void and the consumer will no longer be liable for any amount, including any finance charge. Within 20 calendar days after receipt of a notice of rescission, the lender is required to return any money or property that was given to anyone in connection with the transaction and must take any action necessary to reflect the termination of the security interest. If the lender has delivered any money or property, the consumer may retain possession until the lender has complied with the above.
The consumer may modify or waive the right to rescind if the consumer determines that the extension of credit is needed to meet a bona fide personal financial emergency. To modify or waive the right, the consumer must give the lender a dated written statement that describes the emergency, specifically modifies or waives the right to rescind and bears the signature of all of the consumers entitled to rescind. Printed forms for this purpose are prohibited.
Advertising Disclosure Requirements:
If a lender advertises directly to a consumer, TILA requires the advertisement to disclose the credit terms and rate in a certain manner. If an advertisement for credit states specific credit terms, it may state only those terms that actually are or will be arranged or offered by the lender. If an advertisement states a rate of finance charge, it may state the rate as an “annual percentage rate” (APR) using that term. If the annual percentage rate may be increased after consummation the advertisement must state that fact. The advertisement may not state any other rate, except that a simple annual rate or periodic rate that is applied to an unpaid balance may be stated in conjunction with, but not more conspicuously than, the annual percentage rate.
(The closed-end rescission rules discussed in this article are found in Regulation Z 226.23. The open-end rescission rules are in Regulation Z 226.15.)
Who is able to rescind a loan?
The right of rescission doesn’t apply just to borrowers. All consumers who have an ownership interest in the property have the right to rescind.
What does the right of rescission require of lenders?
The right of rescission requires lenders to provide certain “material disclosures” and multiple copies of the right of rescission notice to EACH owner of the property. Following proper disclosures, lenders must wait at least three business days (until you are reasonably satisfied that the owners have not rescinded) before disbursing loan proceeds.
When does the three-day rescission time clock begin to tick?
The three-day right of rescission period begins once the material disclosures and notice have been given, and lasts three full business days. Business days are defined by Regulation Z to include all calendar days except Sundays and federal holidays. Saturday IS considered a business day for rescission purposes, regardless of whether your offices are open.
In order to properly complete the Notice of Right to Rescind form, you need to know how to calculate the rescission period. Consider the following example.
Assume a closing is set for Thursday, November 15th, 2001, and that all material disclosures and notices are provided to the parties at that time. The rescission period would run:
Friday, November 16, 2001;
Saturday, November. 17, 2001, and
Monday, November 19, 2001.
Sunday is not counted since it is not considered a business day. The rescission period would end at midnight on November 19, 2001.
When may a borrower waive the right of rescission?
Regulation Z allows borrowers to waive their rescission rights, but this exception only applies in very limited circumstances. The law is protective of the right of rescission, and Lenders should be too.
Borrowers may waive their rescission rights and receive their loan proceeds immediately only if they have what is called a “bona fide personal financial emergency.” This means a financial emergency of the magnitude that waiting an additional three days will be personally or financially devastating to the borrower. It might include situations involving natural disasters such as flooding, or a medical emergency that requires immediate funds. When this type of situation does arise, the borrower must provide a written explanation of his or her circumstances to the financial institution. This is not a document that you should draft for the borrower.
Waiving the right of rescission is not a common practice, mostly because doing it wrong can backfire and create a rescindable loan, causing all kinds of problems for the Lender down the road.
advice to Lenders
What happens once the rescission period is over?
After the right-of-rescission period has expired, make sure you feel reasonably certain that the consumer has not rescinded before you disburse the loan proceeds. There are some risks in disbursing after the third day. For example, the law allows consumers to exercise their rescission rights by mail, and a rescission is effective when mailed. Thus, a rescission mailed on the third day after closing is effective even though the lender may not receive it until the fourth or fifth day after the closing. Because of this potential timing problem, Regulation Z suggests that lenders take extra precautions to ensure that the loan has not been rescinded.
To avoid further delay of the loan proceeds, you may want to obtain a confirmation statement from all the owners stating that they have not exercised their rescission rights. Such a written confirmation provides written documentation that the transaction has not been rescinded. Bankers Systems’ rescission forms contain this confirmation language, which can be an effective way to resolve the rescission issue quickly.
(Note, however, that owners should not sign this confirmation until after the three day period is over. Otherwise, it may look like they have improperly waived their rescission rights.)
What are the consequences of noncompliance?
There are serious consequences for failing to follow the right-of-rescission rules. First, until a lender provides the material disclosures and the proper Notice of Right to Rescind, the three-business day rescission period does not start to run, and the transaction remains rescindable for up to three years. And once a consumer rescinds a transaction, the security interest in the property becomes void and you must reimburse the consumer for all of the finance charges collected over the life of the loan.
VIOLATIONS OF TRUTH IN LENDING ACT
Creditors are liable for violation of the disclosure requirements, regardless of whether the consumer was harmed by the nondisclosure, UNLESS:
The creditor corrects the error within 60
days of discovery and prior to written suit or written notice from the consumer, or
The error is the result of bona fide error. The creditor bears the burden of proving by a preponderance of the evidence that:
If the violation was unintentional.
The error occurred notwithstanding compliance with procedures reasonably adapted to avoid such error. (Error of legal judgment with respect to creditor’s TILA obligations not a bona fide error.)
Civil remedies for failure to comply with TILA requirements:
Action may be brought in any U.S. district court or in any other competent court within one year from the date on which the violation occurred. This limitation does not apply when TILA violations are asserted as a defense, set-off, or counterclaim, except as otherwise provided by state law.
Private remedies – applicable to violations of provisions regarding credit transactions, credit billing, and consumer leases.
Actual damages in all cases.
Attorneys’ fees and court costs for successful enforcement and rescission actions.
Statutory damages.
For individual actions, double the correctly calculated finance charge but not less than $100 or more than $2,000 for individual actions.
For class actions, an amount allowed by the court with no required minimum recovery per class member to a maximum of $500,000 or 1% of the creditor’s net worth, whichever is less.
Damages can be imposed on creditors who fail to comply with specified TILA disclosure requirements, with the right of rescission, with the provisions concerning credit cards, or with the fair credit billing requirements.
15 STEPS TO BRING THE LENDER TO THE BARGAINING TABLE.
The following process is administrative. Each Mortgage is based on its own merits; you may have more steps and it may be necessary to go to court at additional expense.
Mortgage must have closed after September 1995, If before September 1995 it is recommended that you refinance.
- Examine Mortgage documents for TILA violations (each violation is worth $2,000.00 in fines)
- Write rescission letter to Lender and Agents
- Send rescission letter to Lender and Agents certified mail
- Wait 20 days for Lender and Agents to respond
- Receive Lenders response (if any; usually the Lender defaults)
- Write default letter to Lender and Agents
- Send default letter to Lender and Agents certified mail
- Write “Qualified Written Request”
- Send “Qualified Written Request” letter to Lender and Agents certified mail
- Wait 60 days
- File complaint (lawsuit)
- Lender may respond by sending many (300) pages of fluff. (stall tactics) In some cases Lender will make offer to settle
- You negotiate to void Lenders security interest in the property and demand payment of violations fines and free and clear title. (all of these damages may not be available in your case)
- Lender agrees
- Security interest in the property is voided and You collect violation fines and Lender gives you clear Title.
Usually when the Lender gets the “Qualified Written Request” letter they will call a meeting with the Borrower and want to negotiate an out of court settlement.
If they are convicted of T.I.L.A. violations they may lose their Federal Reserve
Charter.
The following is an example of some of the TILA violations you will find in your closing documents.
Over-escrowing
Junk charges
(i.e. yield spread premiums and service release fees)
Payment of compensation to mortgage brokers and originators by lenders
Unauthorized servicing charges
(i.e. the imposition of payoff and recording charges)
Improper adjustments of interest on adjustable rate mortgages
Upselling
Overages
Referral fees to mortgage originators.
(i.e. a lender who pays a mortgage broker secret compensation may face liability for inducing the broker to breach his fiduciary or contractual duties, fraud, or commercial bribery)
Failure to disclose the circumstances under which private mortgage insurance (”PMI”) may be terminated.
Underdisclosure of the cost of credit
Excessive escrow deposits
Breach of Fiduciary Duty
TO GET A FREE CONSULTATION
NOW CLICK HERE!
CASE LAW
Truth In Lending Act
Truth in Lending Act was passed to prevent unsophisticated consumer from being misled as to total cost of financing. Truth in Lending Act, Section 102, 15 U.S.C.A. Section 1601. Griggs v. Provident Consumer Discount. 680 F.2d 927, certiorari granted, vacated 103 S.Ct. 400, 459 U.S. 56, 74 L.Ed.2d 225, on remand 699 F.2d 642.
Purpose of Truth in Lending Act is for customers to be able to make informed decisions. Truth in Lending Act Section 102, 15 U.S.C.A. Section 1601. Griggs v. Provident Consumer Discount Co. 680 F.2d 927, certiarari granted, vacated 103 S.Ct. 400, 459 U.S. 56, 74 L.Ed,2d 225, on remand 699 F,2d 642,
Truth in Lending Act is strictly liability statute liberally construed in favor of consumers. Truth in Lending Act Section 102 et seq., 15 U.S.C.A. Section 1601 et seq. Brophv v. Chase Manhattan Mortgage Co, 947 F.Supp. 879.
Truth in Lending Act should be construed liberally to ensure achievement of goal of aiding unsophisticated consumers so that consumers are not easily misled as to total costs of financing. Truth in Lending Act, Sections 102 et seq, 102(a), 105 as amended, I5 U.S.C.A. Sections 1601 et seq., 1601(a), 1604; Truth in Lending Regulations, Regulation Z, Sections 226.1 et seq., 226.18, 15 U.S.C.A. foil. Section 1700, Basile v. H&R Block. Jlt(L. 897 F.Supp. 194.
Truth in Lending Act must be strictly construed and liability imposed for any violation, no matter how technical. Truth in Lending Act Section 102 et seq., as amended, 15 U.S.C.A. Section 1601 et seq, Abele v. Mid-Penn Consumer Discount. 77 B.R. 460, affirmed S45 F.2d 1009.
Truth in Lending Act must be liberally construed to effectuate remedial purposes of protecting consumer against inaccurate and unfair credit billing and credit card practices and of promoting intelligent comparison shopping by consumers contemplating the use of credit by full disclosure of terms and conditions of credit card charges, Truth in Lending Act Section 102 et seq, as amended, 15 U.S.C.A. Section 1601 et seq Lifschitz v. American Exp. Co. 560 F.Supp. 458
To qualify for protection of Truth in Lending Act [15 U,S,C,A. Section 1601 et seq.], plaintiff must show that disputed transaction was a consumer credit transaction not a business transaction, Truth b Lending Act, Section 102 et seq., 15 U.S.C.A. Section 1601 et seq. Quino v A-I CredjlCom. 635 F.Supp. 151
Requirements of Truth in Lending Act are highly technical, but full compliance is required; even minor violations of Act cannot be ignored, Truth in Lending Act, Section 102 et seq. as amended, 15 U.SC.A. Section 1601 et seq.; Truth in Lending Act Regulations, Regulation Z Section 226.1 et seq., 15 U.S.C.A. foil. Section 1700. Griggs v. firpyideot Consumer Discount Co.r 503 F.Supp. 246, appeal dismissed 672 F2d 903, appeal after remand 680 F.2d 927, certiorari granted, vacated 103 S.Ct, 400, 459 U.S. 56, 74 L.Ed.2d 225, on remand 699 F,2d 642.
A valid rescission of a “credit sale” contract does not render inoperative the disclosure requirements of the Truth in Lending Act, as creditor’s obligations to make specific disclosures arises prior to consummation of transaction. Truth in Lending Act Section 102 et seq., 15 U.S.C.A. Section 1601 et seq.; Truth in Lending Regulations, Regulation Z, Sections 226.2(fck)> 226.8(a), 15 U.S.C.A, following section 1700. O’Neil c^ 484 F.Supp. 18.
Under truth in lending regulation providing that disclosure of terras of consumer credit loan shall not be “stated, utilized or placed so as to mislead or confuse” consumer, placement of disclosures is to be considered along with their statement and use. Truth in Lending Regulations, Regulation Z, Section 226.6(c), 15 U.S,C A. following section 1700 .Geimuso v. Commercial Bank & Trust Co.. 566 F.2d 437.
Any violation of the Truth in Lending Act, regardless of technical nature, must result in finding of liability against lender. Truth in Lending Regulations, Regulation Z Section 226.1 et seq., 15 U.S.C.A. foil. Section 1700; Truth in Lending Act Section 130 (a, e), IS U.S.C.A. Section 1640 (a, e). In Re Steinbrecher. 110 B,R. 155, 116 A.L.R. Fed. 881.
Question of whether lender’s Truth in Lending Act disclosures are inaccurate, misleading or confusing ordinarily will be for fact finder; however, where confusing, misleading and inaccurate character of disputed disclosure is so clear that it cannot reasonably be disputed, summary judgment for plaintiff is appropriate Truth in Lending Act Section 102 et seq-; Truth in Lending Regulations, Regulation Z, Section 226.1 et seq., 15 U.S.C.A. foil. Section 1700. Griggs v. Provident Consumer Discount Co.. 503 F, Supp 246, appeal dismissed 672 F.2d 903, appeal after remand 680 F.2d 927, certiorari granted, vacated 103 S.Ct, 400, 459 U.S. 56, 74 L.Ed.2d 225, on remand 699 E2d 642.
Pursuant to regulations promulgated under Truth in Lending Act, violator of disclosure requirements is held to standard of strict liability, and therefore, borrower need not show that creditor in fact deceived biro by making substandard disclosures. Truth in Lending Act, Sections 102-186, as amended, 15 U.S.C.A. Section 1601-1667e; Truth in
Lending Regulations, Regulation Z, Section 226,8(b-d), 15 U.S.C.A. foil. Section 1700 Soils v. Fidelity Consumer Discount Co., 58 B.R. 983,
Once a creditor violates the Truth In Lending Act, no matter how technical violation appears, unless one of statutory defenses applies, Court has no discretion in imposing liability Truth in Lending Act, Sections 102-186 as amended, 15 U.SC.A. Section 1601-1667e. Solis v. Fidelity Consumer Discount Co. 58 B.R, 983.
Under the facts at hand the Plaintiff Bank has patently violated the Truth in Lending Act, At all relevant times the Bank misled and attempted to confuse Defendant. The Bank did not provide appropriate disclosure as required by the Truth in Lending Act in a substantive and technical manner.
“It is not necessary for recession of a contract that the party making the misrepresentation should have known that it was false, but recovery is allowed even though misrepresentation is innocently made, because it would be unjust to allow one who made false representations, even innocently, to retain the fruits of a bargain induced by such representations.” Whipp v. Iverson, 43 Wis 2d 166.
“If any part of the consideration for a promise be illegal, or if there are several considerations for an unseverable promise one of which is illegal, the promise, whether written or oral, is wholly void, as it is impossible to say what part or which one of the considerations induced the promise.” Menominee River Co. v. Augustus Spies L & C Co., 147 Wis 559, 572; 132 NW 1122
“When an instrument [notes] lacks an unconditional promise to pay a sum certain at a fixed and determined time, it is only an acknowledgement of the debt and statutory presumptions like the presence of a valuable consideration, are not applicable.” Bader vs. Williams, 61 A 2d 637
“Any false representation of material facts made with knowledge of falsity and with intent that it shall be acted on by another in entering into contract, and which is so acted upon, constitutes ‘fraud,’ and entitles party deceived to avoid contract or recover damages.” Barnsdall Refining Corn. v. Birnam wood Oil Co., 92 F 2d 817.
“In the federal courts, it is well established that a national bank has not power to lend its credit to another by becoming surety, indorser, or guarantor for him.” Farmers and Miners Bank v. Bluefield Nat ‘l Bank, 11 F 2d 83, 271 U.S. 669.
“A national bank has no power to lend its credit to any person or corporation. .” Bowen v. Needles Nat. Bank, 94 F 925, 36 CCA 553, certiorari denied in 20 S.Ct 1024, 176 US 682, 44 LED 637.
“Mr. Justice Marshall said: The doctrine of ultra vires is a most powerful weapon to keep private corporations within their legitimate spheres and to punish them for violations of their corporate charters, and it probably is not invoked too often . . . Zinc Carbonate Co. v. First National Bank, 103 Wis 125, 79 NW 229.”American Express Co. v. Citizens State Bank, 194 NW 430.
“It has been settled beyond controversy that a national bank, under federal law being limited in its powers and capacity, cannot lend its credit by guaranteeing the debts of another. All such contracts entered into by its officers are ultra vires . . .” Howard & Foster Co. v. Citizens Nat’l Bank of Union, 133 SC 202, 130 SE 759(1926).
“It is not within those statutory powers for a national bank, even though solvent, to lend its credit to another in any of the various ways in which that might be done.” Federal Intermediate Credit Bank v. L ‘Herrison, 33 F 2d 841, 842 (1929).
“A bank can lend its money, but not its credit.” First Nat ‘I Bank of Tallapoosa v. Monroe, 135 Ga 614, 69 SE 1124, 32 LRA (NS) 550.
“. . . the bank is allowed to lend money upon personal security; but it must be money that it loans, not its credit.” Seligman v. Charlottesville Nat. Bank, 3 Hughes 647, Fed Case No.12, 642, 1039.
“The contract is void if it is only in part connected with the illegal transaction and the promise single or entire.” Guardian Agency v. Guardian Mutual. Savings Bank, 227 Wis 550, 279 NW 83.
“Banking Associations from the very nature of their business are prohibited from lending credit.” St. Louis Savings Bank vs. Parmalee 95 U. S. 557
Our mission is to educate homeowners about predatory lending practices and the legal options available to them.
We believe that if you don’t know your rights, you don’t know your options.
38.017951
-122.135262




 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 p.
 13 p.
 226 p.
 28 p.
 2 p.
 96 p.
 34 p.
 44 p.
 48 p.
 85 p.
 112 p.
 14 p.
 126 p.
 9 p.
 15 p.
 243 p.
 113 p.
 150 p.
 79 p.
 44 p.
 64 p.
 49 p.
 50 p.
 31 p.
 24 p.
 24 p.


Add a Comment